There’s a lot of noise in the financial world about the right way to build wealth. To buy the six-dollar latte or save on the small things; to keep your car loan to build credit or keep driving that clunker to stay out of debt; to invest in mutual funds or stick with index funds; to buy while the market dips or get out while you can.
Through all that noise, there is one piece of advice that always seems to rise to the top: buying is always better than renting. While buying a home can be a great way to build wealth, for some, buying may not be the best option. Here are five reasons to consider renting instead of taking the plunge into homeownership.
1. No repair costs or hassles
Dishwashers, water heaters, and roofs have a tendency to stop working. When you own your own home, these surprise expenses can have you dipping into your savings to get them back to working condition. When you rent, maintenance and repairs rest on the shoulders of the landlord, giving you the flexibility to invest that extra money or spend it on a beach vacation instead of a new roof.
2. Access to amenities
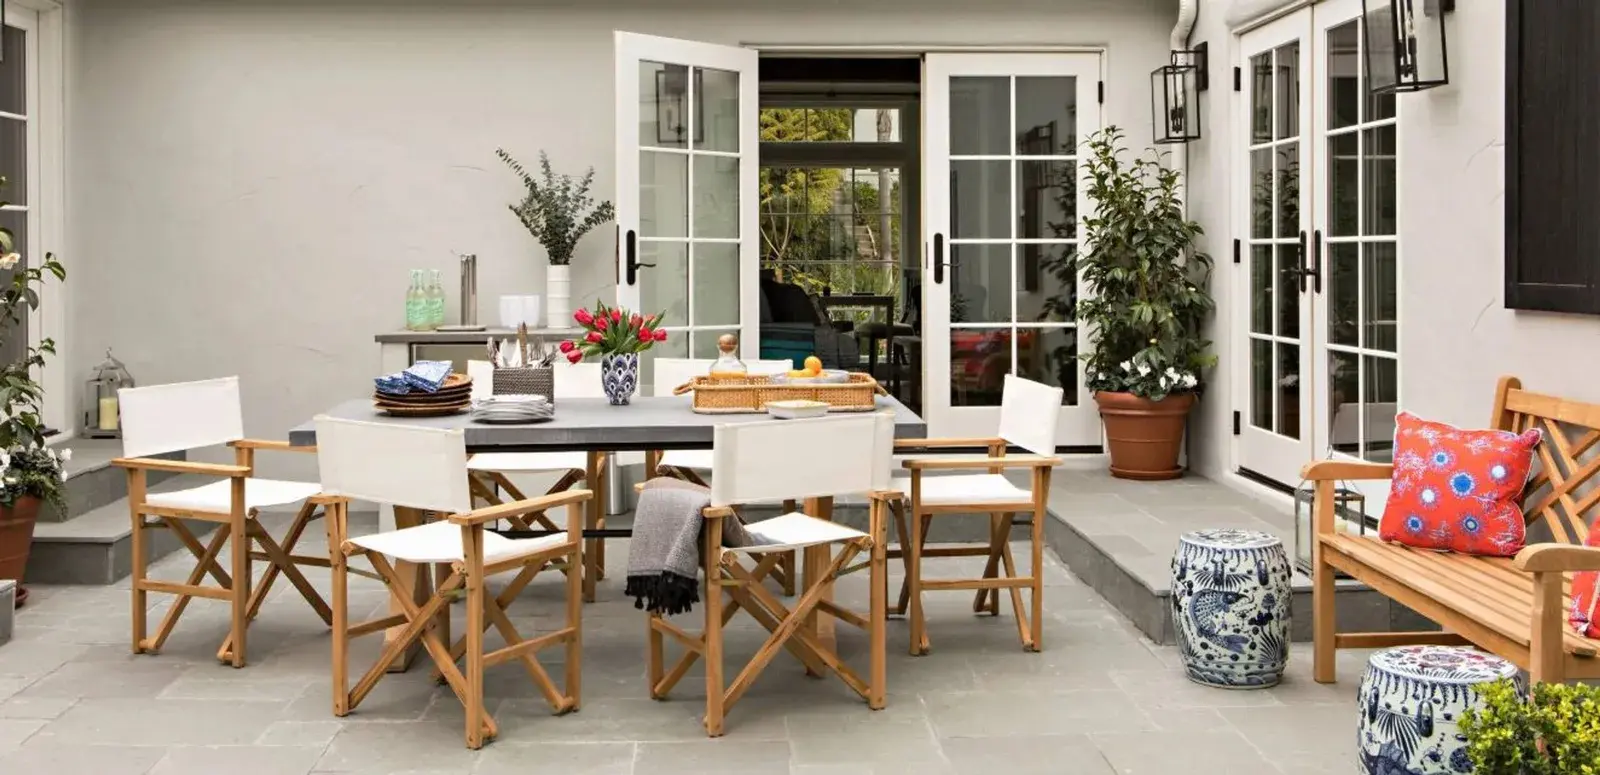
Imagine having a home with a resort-style pool and a private gym. For many of us, owning a home with these features is out of the question. However, many apartment communities offer these amenities for a fraction of the monthly cost of a mortgage with similar features. These amenities are cared for by the apartment’s management team, and all you have to do is sit back and relax by the pool.
3. Less costly
While mortgage payments are often lower than monthly rent payments, many people do not consider the additional costs that come with homeownership. For example, homeowners insurance can be 10 times the cost of renters insurance. Add that to the cost of property taxes, HOA fees, and closing costs and renting quickly starts to look like the better option. An additional point to take into consideration is that national yearly home appreciation sits at just under four percent, while the average rate of return for a diverse investment portfolio sits around seven percent. In simple terms, this means that investing all your money into a home may not always be the most efficient way to build wealth.
4. Moving is much easier
For the first couple of years mortgage payments often only pay the interest plus all those fees mentioned earlier. Moving during that time period means losing a good deal of money. On the other hand, renters have the flexibility to move every time their lease is up or even rent month to month. This allows renters to choose the living situation that works best for them or take a job offer in a new city without worrying about losing money.
5. More free time
Buying a home is obviously a large financial investment, but few consider the time needed to care for a home. Cleaning a larger space, maintaining a well-kept lawn, and updating outdated decor can quickly eat away at your already too-short weekends. Instead of spending your weekends mowing, trimming bushes, and taking trips to Home Depot, why not spend your time relaxing by that pool we mentioned earlier?
Buying a home is a huge financial decision that is often touted as the ticket to financial freedom. However, for some, buying a home means signing up for less money, less time, less flexibility, and ultimately less freedom. For more information on renting and how to make the most out of your renting experience, be sure to follow Becovic Management Group on LinkedIn (opens in a new tab), Facebook (opens in a new tab), and Instagram (opens in a new tab).